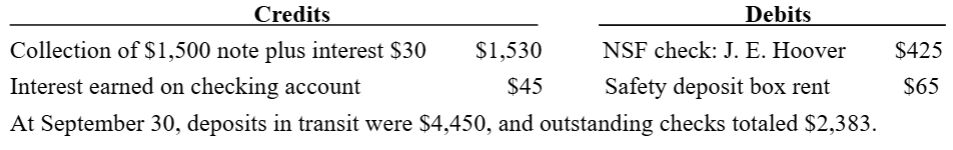所屬科目:研究所、轉學考(插大)◆會計原理
1.Which of the following events is not recorded in the accounting records? (A) Equipment is purchased on account. (B) An employee is terminated. (C) A cash investment is made into the business. (D) The company pays a cash dividend.
2.Which of the following statements is false? (A) A statement of cash of flows summarizes information about the cash inflows (receipts) and outflows (payments) for a specific period of time. (B) A statement of financial position reports the assets, liabilities, and equity at a specific date. (C) An income statement presents the revenues, expenses, changes in equity, and resulting net income or net loss for a specific period of time. (D) A retained earnings statement summarizes the changes in retained earnings for a specific period of time.
3.The expanded accounting equations is : (A) Assets + Liabilities = Share Capital + Retained Earnings + Dividends + Revenues + Expenses (B) Assets = Liabilities + Share Capital + Retained Earnings + Dividends + Revenues Expenses (C) Assets = Liabilities Share Capital – Retained Earnings Dividends Revenues Expenses (D) Assets = Liabilities + Share Capital + Retained Earnings Dividends + Revenues Expenses
4.A trial balance will not balance if : (A) a correct journal entry is posted twice. (B) the purchase of supplies on account is debited to Supplies and credited to Cash. (C) a £ 100 cash dividend is debited to Dividends for £ 1,000 and credited to Cash for £ 100. (D) a £ 450 payment on accounts is debited to Accounts Payable for £ 45 and credited to Cash for £ 45.
5.Each of the following is a major type (or category) of adjusting entries except : (A) prepaid expenses. (B) accrued revenues. (C) accrued expenses. (D) earned revenues.
6.Which types of accounts will appear in the post-closing trial balance ? (A) Permanent (real) accounts. (B) Temporary (nominal) accounts. (C) Accounts shown in the income statement columns of a work sheet. (D) None of the above.
7.The proper order of the following steps in the accounting cycle is : (A) prepare unadjusted trial balance, journalize transactions, post to ledger accounts, journalize and post adjusting entries. (B) journalize transactions, prepare unadjusted trial balance, post to ledger accounts, journalize and post adjusting entries. (C) journalize transactions, post to ledger accounts, prepare unadjusted trial balance, journalize and post adjusting entries. (D) prepare unadjusted trial balance, journalize and post adjusting entries, journalize transactions, post to ledger accounts.
8.If beginning inventory is $60,000, cost of goods purchased is $380,000, and ending inventory is $50,000, cost of goods sold is : (A) $390,000. (B) $370,000. (C) $330,000. (D) $420,000.
9.In periods of rising prices, average-cost will produce : (A) higher net income than FIFO. (B) the same net income as FIFO. (C) lower net income than FIFO. (D) net income equal to the specific identification method.
10.Factors that affect the selection of an inventory costing method do not include : (A) tax effects. (B) statement of financial position effects. (C) income statement effects. (D) perpetual vs. periodic inventory system.
11.The reconciling item in a bank reconciliation on that will result in an adjusting entry by the depositor is : (A) outstanding checks. (B) deposit in transit. (C) a bank error. (D) bank service charges.
12.Which of the following approaches for bad debts is best described as a statement of financial position method ? (A) Percentage-of-receivables basis. (B) Direct write-off method. (C) Percentage-of-sales basis. (D) Both a and b.
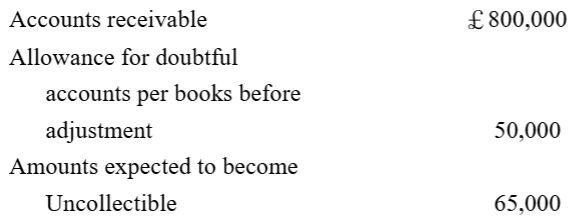
13.An analysis and aging of the accounts receivable of Prince Company at December 31 reveals the following data. The cash realizable value of the accounts receivable at December 31, after adjustment is : (A) £685,000. (B) £750,000. (C) £800,000. (D) £735,000.
14.Which of the following statements is false? (A) If an intangible asset has a finite life, it should be amortized. (B) The amortization period of an intangible asset can exceed 20 years. (C) Goodwill is recorded only when a business is purchased. (D) Development costs are always expensed when incurred.
15.Preference shares may have priority over ordinary shares except in : (A) dividends. (B) assets in the event of liquidation. (C) cumulative dividend features. (D) voting.
16.On January 1, Besalius Inc. issued $1,000,000, 9% bonds for $939,000. The market rate of interest for these bonds is 10%. Interest is payable annually on December 31. Besalius uses the effective-interest method of amortizing bond discount. At the end of the first year, Besalius should report unamortized bond discount of : (A) $54,900. (B) $57,100. (C) $51,610. (D) $51,000
17.The ledger of JFK, Inc. shows share capital-ordinary, treasury shares-ordinary, and no preference shares. For this company, the formula for computing book value per share is : (A) Total equity divided by the number of ordinary shares issued. (B) Share capital-ordinary divided by the number of ordinary shares issued. (C) Total equity divided by the number of ordinary shares outstanding. (D) Share capital-ordinary divided by the number of ordinary shares outstanding.
18.Assume that Horicon Co. acquired 25% of the ordinary shares of Sheboygan Co. on January 1, 2011, for $300,000. During 2011, Sheboygan Co. reported net income of $160,000 and paid total dividends of $60,000. If Horicon uses the equity method to account for its investment, the balance in the investment account on December 31, 2011, will be: (A) $300,000. (B) $325,000. (C) $400,000. (D) $340,000
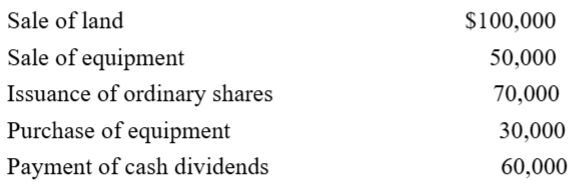
19.The following data are available for Orange Peels Corporation. Net cash provided by investing activities is : (A) $120,000. (B) $130,000. (C) $150,000. (D) $190,000
20.The following schedule is a display of what type of analysis ?(A) Horizontal analysis. (B) Differential analysis. (C) Vertical analysis. (D) Ratio analysis.
(a) Prepare the entry to record the exchange of assets by Sidney Co. (3%)
(b) Prepare the entry to record the exchange of assets by Lupa Inc. (3%)
參、Heath Cosmetics acquired 15% of the 200,000 ordinary shares of Van Fashion at a total cost of $13 per share on March 18, 2011. On June 30, Van declared and paid a $60,000 dividend. On December 31, Van reported net income of $122,000 for the year. At December 31, the market price of Van Fashion was $15 per share. The shares are classified as available-for-sale. Instructions Prepare all the necessary journal entries for 2011 for Heath Cosmetics. (9%)
肆、The ledger of Hixson Company at the end of the current year shows Accounts Receivable € 120,000, Sales € 840,000, and Sales Returns and Allowances € 30,000. Instructions If Allowance for Doubtful Accounts has a debit balance of € 200 in the trial balance, journalize the adjusting entry at December 31, assuming bad debts are expected to be (1)0.75% of net sales and (2) 6% of accounts receivable. (6%)
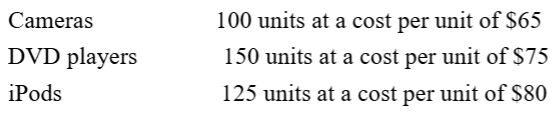
伍、Conan Company applied FIFO to its inventory and got the following results for its ending inventory. The net realizable value per unit at year-end was cameras $71, DVD players $69, and iPods $78. Instructions Determine the amount of ending inventory at lower-of-cost-or-net realizable value. (6%)
陸、The information below relates to the Cash account in the ledger of Robertson Company. Balance September 1-$17,150; Cash deposited-$64,000. Balance September 30-$17,404; Checks written-$63,746. The September bank statement shows a balance of $16,422 on September 30 and the following memoranda. Prepare the bank reconciliation at September 30. (8%)
(a) There are no preference dividends in arrears, and the preference shares do not have a call price. (4%)
(b) Preference dividends are one year in arrears, and the preference shares have a call price of £60 per share. (4%)
(a) cash payments to suppliers and
(b) cash payments for operating expenses.
(a) Earnings per share.
(b) Price-earnings.
(c) Times interest earned.
 阿摩線上測驗
登入
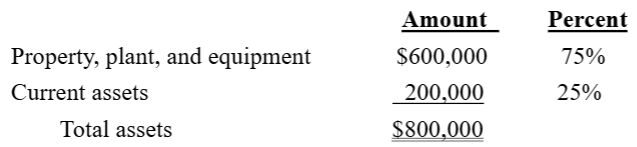 (A) Horizontal analysis. (B) Differential analysis. (C) Vertical analysis. (D) Ratio analysis.