所屬科目:研究所、轉學考(插大)◆中級會計學
1. The controller for Haley Corporation is concerned about certain business transactions that the company experienced during 2022. The controller, after discussing these matters with various individuals, has come to you for advice. The transactions at issue are presented below. ● The company has decided to switch from the direct write-off method in accounting for bad debt expense to the percentage-of-receivables approach. Assume that Haley Corporation has recognized bad debt expense as the receivables have actually become uncollectible in the following way:The controller estimates that an additional $65,400 will be charged off in 2023: $11,400 applicable to 2021 sales and $54,000 to 2022 sales. ● Inventory has been shipped on consignment. These transactions have been recorded as ordinary sales and billed as such on account. At December 31, 2022, inventory billed and in the hands of consignees amounted to $400,000. The percentage markup on selling price is 20%. Assume that consigned inventory is sold the following year. The company uses the perpetual inventory system. Instructions Assume that Haley Corporation reported net income of $1,000,000 for 2022. What is the corrected net income after reviewing the above transactions?
2. Howard Corp. sponsors a defined-benefit pension plan for its employees. On January 1, 2022, the following balances related to this plan.As a result of the operation of the plan during 2022, the actuary provided the following additional data at December 31, 2022. Instructions What is the pension expense for Howard Corp. for the year 2022?
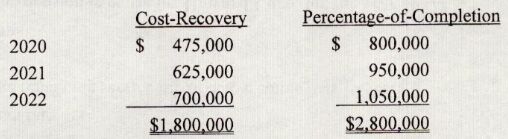
3. During 2022, a construction company changed from the cost-recovery method to the percentage-of-completion method for accounting purposes but not for tax purposes. Gross profit figures under both methods for the past three years appear below: Assuming an income tax rate of 40% for all years, the effect of this accounting change on prior periods should be reported by a credit of what amount on the 2022 retained earnings statement?
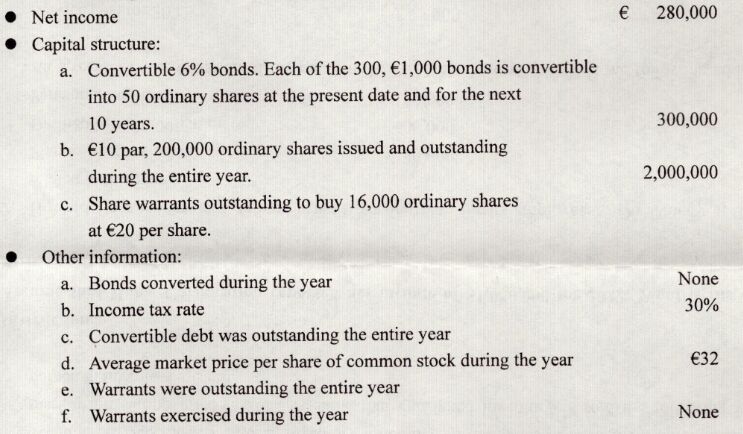
4. The following information was taken from the books and records of Ludwick, Inc.: Instructions Compute diluted earnings per share.
5. Halvor Corporation is having financial difficulty and therefore has asked Manhattan National Bank to restructure its €3 million note outstanding. The present note has 3 years remaining and pays a current rate of interest of 10%. The present market rate for a loan of this nature is 12%. The note was issued at its face value. Manhattan National Bank agrees to modify the terms of the note, indicating that Halvor does not have to pay interest on the note over the 3-year period. Instructions Compute the gain on the extinguishment of debt that Halvor would make for the restructuring.
第二大題(共 25 分)-假設每一小題為獨立狀況 1. 騰龍公司在計算 X4 年到 X6 年的會計利潤與課稅所得時發現有下列幾項差異: (1)X3年底資產負債表上有估計產品保證負債$200,000,依稅法規定產品保證費用於實際發生時方可認列。X4年底到X6年底騰龍公司帳上的估計產品保證負債分別為$95,000、$160,000及$120,000。 (2)投資國營事業所得在X4年到X6年分別為$200,000、$200,000、$150,000,依稅法規定投資國營事業所得為免稅。 (3)騰龍公司在X1年以$800,000所購入的一項資產估計可使用八年,無殘值,帳上依直線法提列折舊。在報稅上,則依稅法規定採計五年,同樣使用直線法無殘值。 騰龍公司 X4 年到 X6 年的會計利潤分別為$5,500,000、$4,400,000 及$3,300,000,而稅率皆為 20%。試作:計算 X6 年本期應付所得稅為何?
2. 雅萱公司於 X3 年 1 月 1 日發行可轉換公司債給雨呈公司,該可轉換公司債的公允價值為$250,000,公司債面額為$200,000,票面利率為 5%,每年 12 月 31 日付息一次,發行期限為 5 年,轉換價格為$50。經客觀評價之後認定發行時不含轉換權之公司債公允價值為$230,000,轉換權之公允價值為$50,000。雅萱公司在發行時,發生$2,500 直接交易成本,而雨呈公司在買入時,發生$1,300 直接交易成本。假設不考慮所得稅利益之效果時: 試問:X3 年 1 月 1 日雅萱公司發行可轉換公司債其中公司債部分之帳面金額為何?
3. 全球公司將其旗下所有歌手之歌曲授權予史蒂芬音樂平台公司使用,雙方於 X1 年 12 月 31 日簽訂所有歌手之歌曲授權使用合約,合約中約定史蒂芬音樂平台公司於簽約日必須先行支付全球公司 $900,000 一次性的權利金,以取得未來 3 年的音樂授權,並於專利授權期間內自 X2 年 1 月 1 日至 X4 年 12 月 31 日止,每一年底依據史蒂芬音樂平台公司提供該年度之線上收聽次數,每次另行支付權利金 $0.3 予全球公司,每年底按線上收聽次數計算之權利金。史蒂芬音樂平台公司應於次年度 3 月 19 日支付。各年度史蒂芬音樂平台公司每年提供的線上收聽次數如下: 試問:全球公司前述歌手X4年度歌曲授權之權利金收入金額為何?
4. 金門公司於 X1 年初向馬祖公司承租一項運輸設備,租期 5 年,每年之租賃給付為$75,000,於每年年初支付。合約中並附有租賃延長 3 年之選擇權,金門公司於開始日判斷該租賃延長之選擇權之行使並非可合理確定,因此判定租賃期間為 5 年。在開始日時,馬祖公司之租賃隱含利率為 8%,且為金門公司所知,使用權資產按直線法折舊,金門公司預期於租期屆滿日須就保證殘值與估計殘值之差額支付馬祖公司$9,000。在 X4 年初,因金門公司評估繼續承租此設備有其效益,故可合理確定將行使租賃延長之選擇權以延長其原始租賃。X4 年初時租賃隱含利率並非容易確定,金門公司此時之增額借款利率為 7%,並預期在行使延長之選擇權後,於延長後之無須就殘值保證額外支付任何款項。 試問:X4 年金門公司與此租賃相關之利息費用金額為何? (P4.8%=3.312127, p4.8%=0.735030; P5.8%=3.992710, p5.8%=0.680583; P4.7%=3.387211, p4.7%=0.762895; P5.7%=4.100197, p5.7%=0.712986)
5. 小熊公司 X5 年初將一輛卡車以融資租賃出租小虎公司,約定每年年底收取租金$600,000,租期 5 年,租期屆滿日該卡車之估計殘值為 $100,000,小虎公司保證其中 $50,000,並預期租期屆滿日會就殘值保證支付$8,000。該卡車為小熊公司 X4 年所購入,X5 年初時的帳面金額等於公允價值$2,000,000。另外,小熊公司因此項租賃所產生之原始直接成本為 $164,615,於 X5 年初支付。 試問:小熊公司 X6 年認列之利息收入金額為何? (P5.10%=3.790787, p5.10%=0.620921; P5.11%=3.695897, p5.11%=0.593451; P5.12%=3.604776, p5.12%=0.567427; P5.13%=3.517231, p5.13%=0.542760; P5.14%=3.433081, p5.14%=0.519369)
1. 上列各項方案,何種方案對三峽健身中心最有利?(請直接寫方案號碼) 理由為何?(請簡要回答)
2. 三峽健身中心在2020年3月1日將收費方式改為方案2的主要原因為何?(請簡要回答)
3. 假設小明於2021年11月1日加入健身中心並選擇以分計費方式,試問小明可申請退還之金額為多少?理由為何?(試分析各種可能情況)
4. 若小明不接受3.之退費方式,但最後亦未針對糾紛提起申訴,可能原因為何?(請簡要回答)
廠房:____(1)____
機器A:____(2)____
機器B:____(3)____
2. 新北公司於2019年4月1日,以$6,000,000取得某項技術之專利權,估計使用年限為5年。該專利權於2021年3月1日發生侵權官司,2021年7月1日新北公司勝訴,此次訴訟支出金額為$600,000。2022年底,新北公司發現該專利權之技術已有新技術可以取代,故其價值大幅降低。新北公司評估此專利權可回收金額為$300,000。試問2022年底新北公司應認列多少減損損失?____(4)____
3. 北大公司2022年出售2,000台機器並提供一年售後保證服務,依據過去經驗約有6%需提供售後服務,維修成本每台平均為$30。北大公司另外出售二台特殊規格機器(A及B),亦提供客戶一年內免費維修。機器A估計維修成本為$1,000的機率為20%,$2,000的機率為50%,$3,000的機率為30%;機器B估計維修成本為$1,000的機率為60%,$2,000的機率為10%,$3,000的機率為30%。試問北大公司2022年須認列之負債準備為多少?____(5)____
 阿摩線上測驗
登入


 Instructions
